
About
I take complicated things apart so you don't have to
I'm Dominic Kramer, Mortgage Loan Originator, NMLS #1946539. Most people call me their Money Guy. I help buyers, homeowners, and investors in all 50 states get loans that actually close, usually in about 15 days or less.
Why I'm here for you
I did not start in a bank. I started a painting company out of high school, sold it, then spent years in hospitality, auto sales, and eventually auto finance where I closed thousands of loans and learned how the money actually moves. That path taught me something useful: the person on the other side of the desk usually has no idea how the machine works, and that information gap costs them real money.
When I got into mortgages, I saw the same gap. Big words, hidden layers, rate quotes that don't match the closing disclosure. So I built this site and my process around one idea: you should understand your loan at least as well as the person selling it to you. Not because you want to become a loan officer, but because it's your money, your house, and your future payment.
I am competitive, curious, and a little obsessive. When something grabs me, I will tear it apart at 2 a.m. until I find the better way. ADHD is part of my operating system. It is a superpower when I am locked in and a curse when I am not. The good news for you: mortgages lock me in. There is always a smarter structure, a cleaner process, or a way to save you a few thousand dollars.
How I actually work
Most people show up with three questions: what can I afford, what will it really cost, and what could go wrong. I start there. Before program names, before rate quotes, before anything else. The loan structure should follow your life, not the other way around.
From there we get specific. I verify income the way an underwriter will, source every deposit, model two or three loan options side by side, and set contract dates the file can realistically hit. I have worked with first-time buyers, move-up buyers, self-employed borrowers, veterans, homeowners weighing a refinance, and investors scaling from one door to several. Being licensed nationwide means a relocation does not force you to start over with a stranger.
What you can count on
The right answer might be 'not yet'
If waiting six months to clean up credit or build reserves puts you in a materially better loan, that's the advice you'll get, even though it delays my paycheck.
Pre-approval means underwritten
A letter generated from a five-minute conversation isn't worth much. I review documents up front so your approval survives contract, appraisal, and underwriting.
Show the whole cost
Monthly payment, cash to close, and lifetime interest. Every scenario I present includes all three, because optimizing only for the payment hides real money.
Answer the phone
Deals move on evenings and weekends. Your agent, your escrow officer, and you should all be able to reach me when it counts.
The thing I keep learning
Every business I have run, from auto sales to remodeling to software, comes back to the same question: what is the actual right answer here? Not the easiest sale. Not the biggest commission. The right answer for this person, right now. That is the filter I use for every loan I structure. If I would not do it with my own money, I will not recommend it with yours.
Off the clock
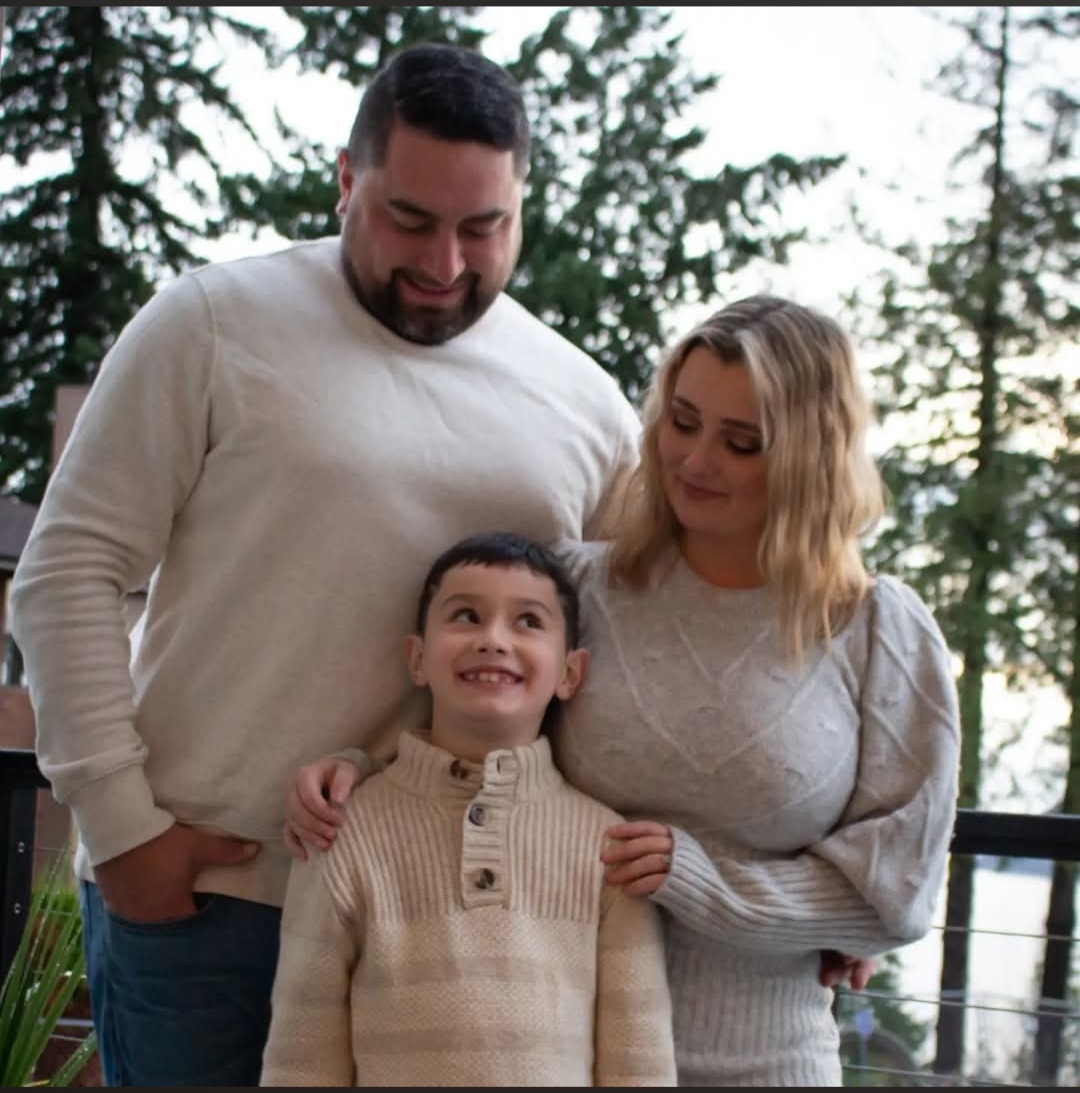
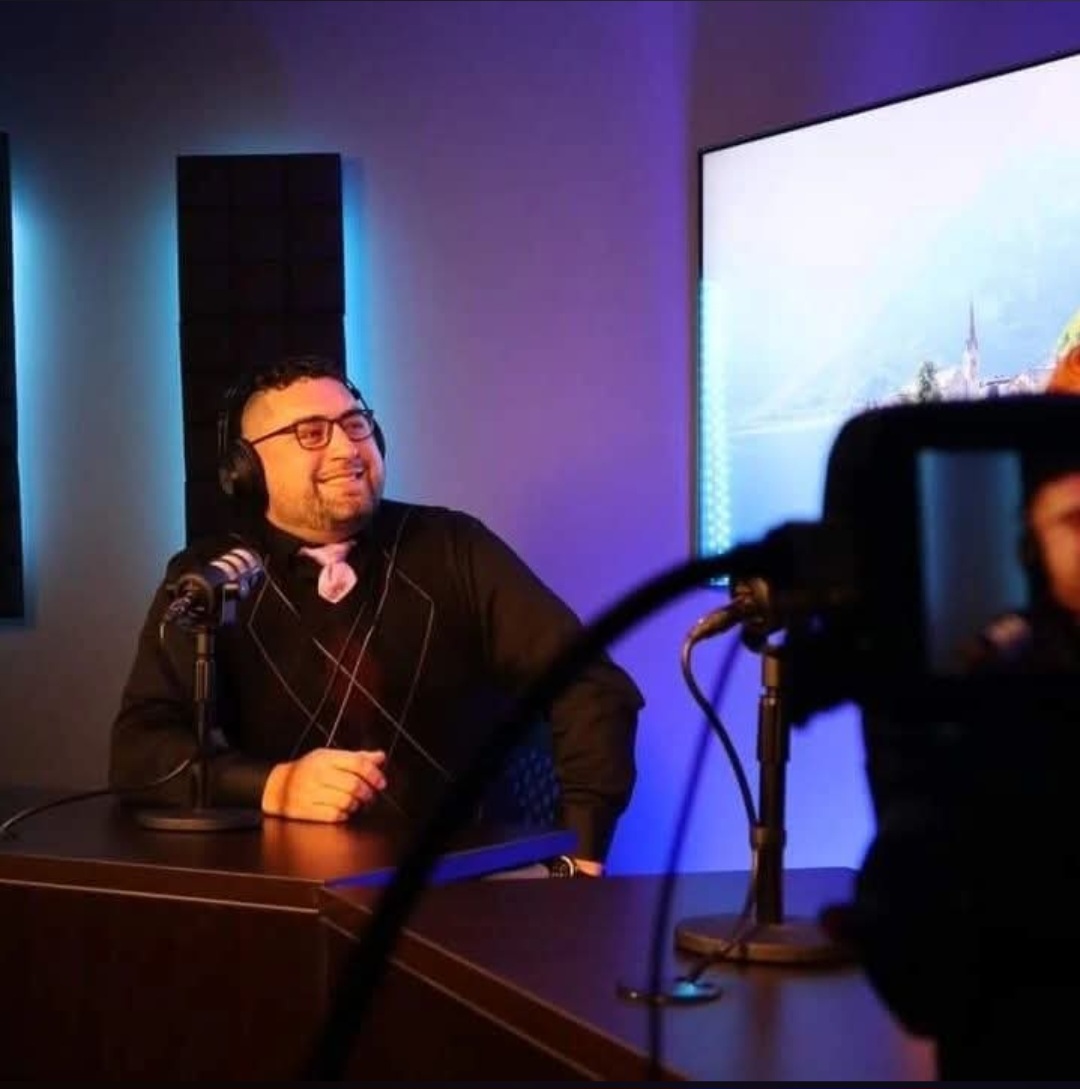
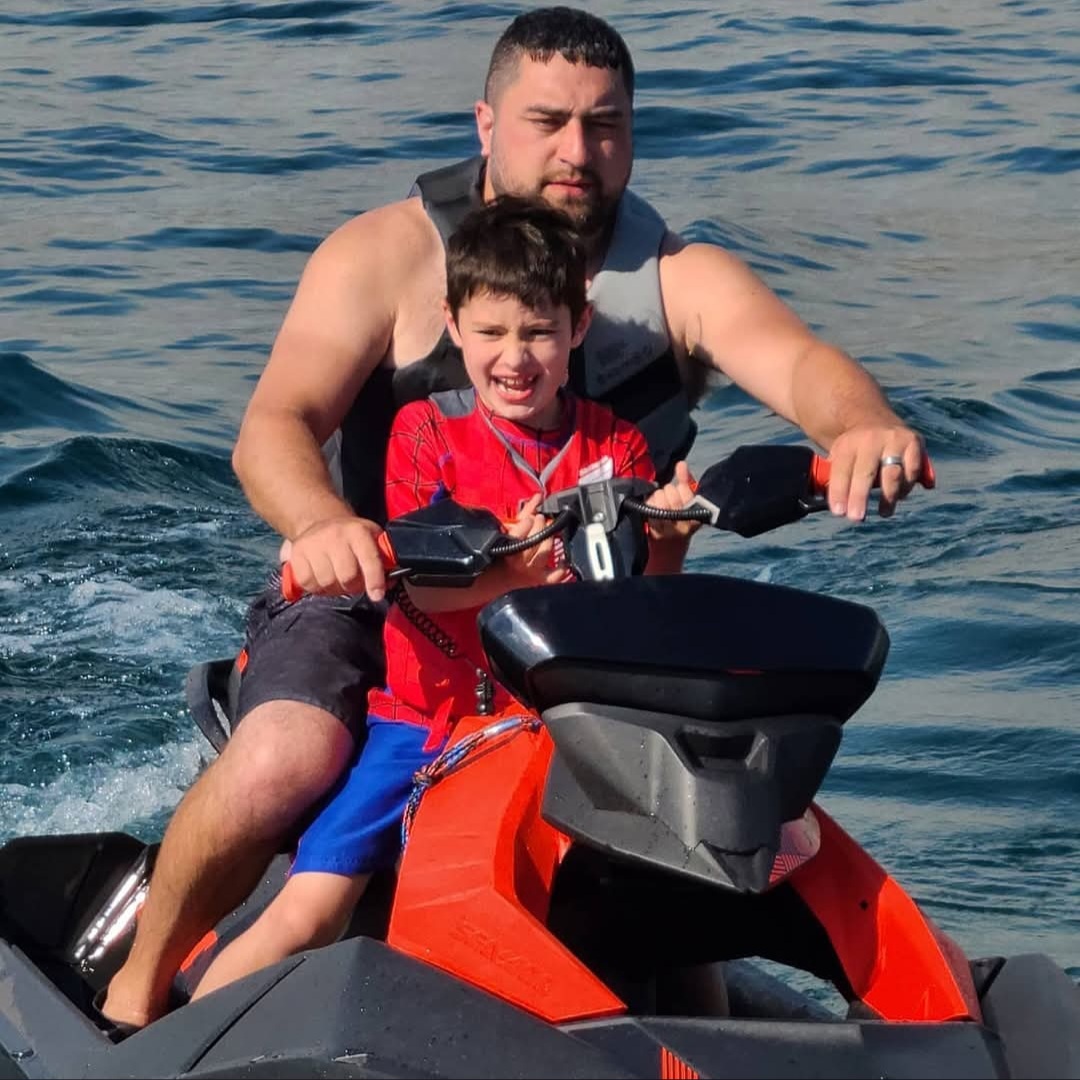
Life outside the loan file

Let's look at your situation
Bring the messy version. Variable income, a home to sell, credit you're working on, a deal that needs to close fast. That's the interesting part of the job.